It is easy to fall in love with a kitchen before you have figured out the rest of the purchase. That is part of what makes buying your first home exciting—and occasionally overwhelming. A little preparation gives you room to enjoy the search without making every decision under pressure. Whether you are looking in Oakland, Wayne, or Macomb County, begin with the way you want to live and work outward from there.
Choose a home that works for your life after closing, not only for the day you tour it.
Your priorities
Your financing
The property
Closing & keys
Start with your daily life
Write down the things a home needs to make possible: your commute, work space, storage, outdoor space, and the amount of upkeep you want. Separate essentials from preferences. A kitchen can change; the location and lot usually cannot. Use the same short checklist at every showing so a memorable feature does not distract from a missing essential.
Be specific about what “enough space” means. If you work from home three days a week, a quiet room with a door may matter more than a larger dining room. If you own tools, bikes, or seasonal equipment, inspect the storage rather than counting closets. Drive the routes you expect to use at the times you expect to use them. Photos cannot tell you how a location fits your ordinary Tuesday.
Get a realistic financing picture
Talk with a lender about your available loan options and the documents needed for pre-approval. Ask for estimated monthly costs and cash needed to close, then compare those numbers with your own comfort level. Leave room for moving and repairs. A pre-approval is a useful starting point, but final approval still depends on the lender’s review and the property.
Build two separate numbers: a comfortable monthly payment and the cash you can use without draining your cushion. Include taxes, insurance, any association dues, utilities, and maintenance in your thinking. Then ask the lender to explain what is included in its estimate. Two homes at the same asking price can have different ownership costs. A lender’s maximum approval and your preferred budget do not have to be the same number.
Picture this
You tour two homes at a similar price. One has updated finishes but requires a long daily drive and has little storage. The other needs paint, but its layout, location, and garage work for your routine. Neither is automatically the better purchase. Put the monthly costs, necessary projects, and everyday tradeoffs beside each other before deciding which one deserves an offer.
Tour with a plan, then investigate
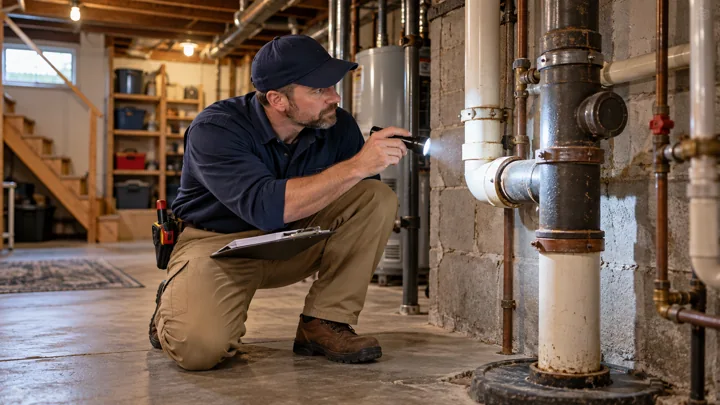
Take notes on layout, storage, visible condition, and questions that need an expert. Once you have an accepted offer, arrange an independent inspection promptly. An inspection addresses condition; an appraisal addresses value. Your contract determines the deadlines and options for responding to problems. Avoid treating attractive finishes as proof that major systems are in good shape.
At a showing, try opening the pantry, imagining where laundry will go, and checking how rooms connect. Write down questions while you are there: How old is the heating equipment? Has water entered the basement? What stays with the home? Your agent can help request information, while an inspector or other specialist can evaluate condition. A showing helps you decide whether to investigate; it is not a substitute for that investigation.
Stay organized through closing
Keep documents and lender requests in one place. Before making a major financial change during the purchase, ask your lender how it could affect the loan. Review the closing paperwork, arrange utilities, and confirm possession timing. On the final walkthrough, check the property against the agreement and raise unresolved issues before signing.
Ask your agent to put the major dates on a simple calendar: deposit, inspection response, financing milestones, closing, and possession. Keep a running list of who needs what from you. Before closing, confirm the transfer-of-funds instructions directly with the closing company using a trusted phone number. Pack a first-night bag separately from the moving truck, including medication, chargers, toiletries, and anything you will need if unpacking takes longer than planned.
Questions you may be asking
Do I need to know exactly what I want before speaking with an agent?
No. Bring a starting budget, your timing, and a few things your next home needs to do for you. Early conversations and a small number of well-chosen showings can help refine your priorities.
What should I avoid after getting pre-approved?
Before opening credit, changing jobs, financing furniture, or moving large sums of money, ask your lender how the change could affect your application. Keep providing requested documentation until the loan is complete.
Your next steps
- Write down five must-haves.
- Ask a lender for a personalized estimate.
- Set aside time for inspection and final review.
Further reading
CFPB: Schedule a home inspection ↗Sources checked October 10, 2026. Verify current requirements with the relevant provider.